Credit Utilisation Ratio
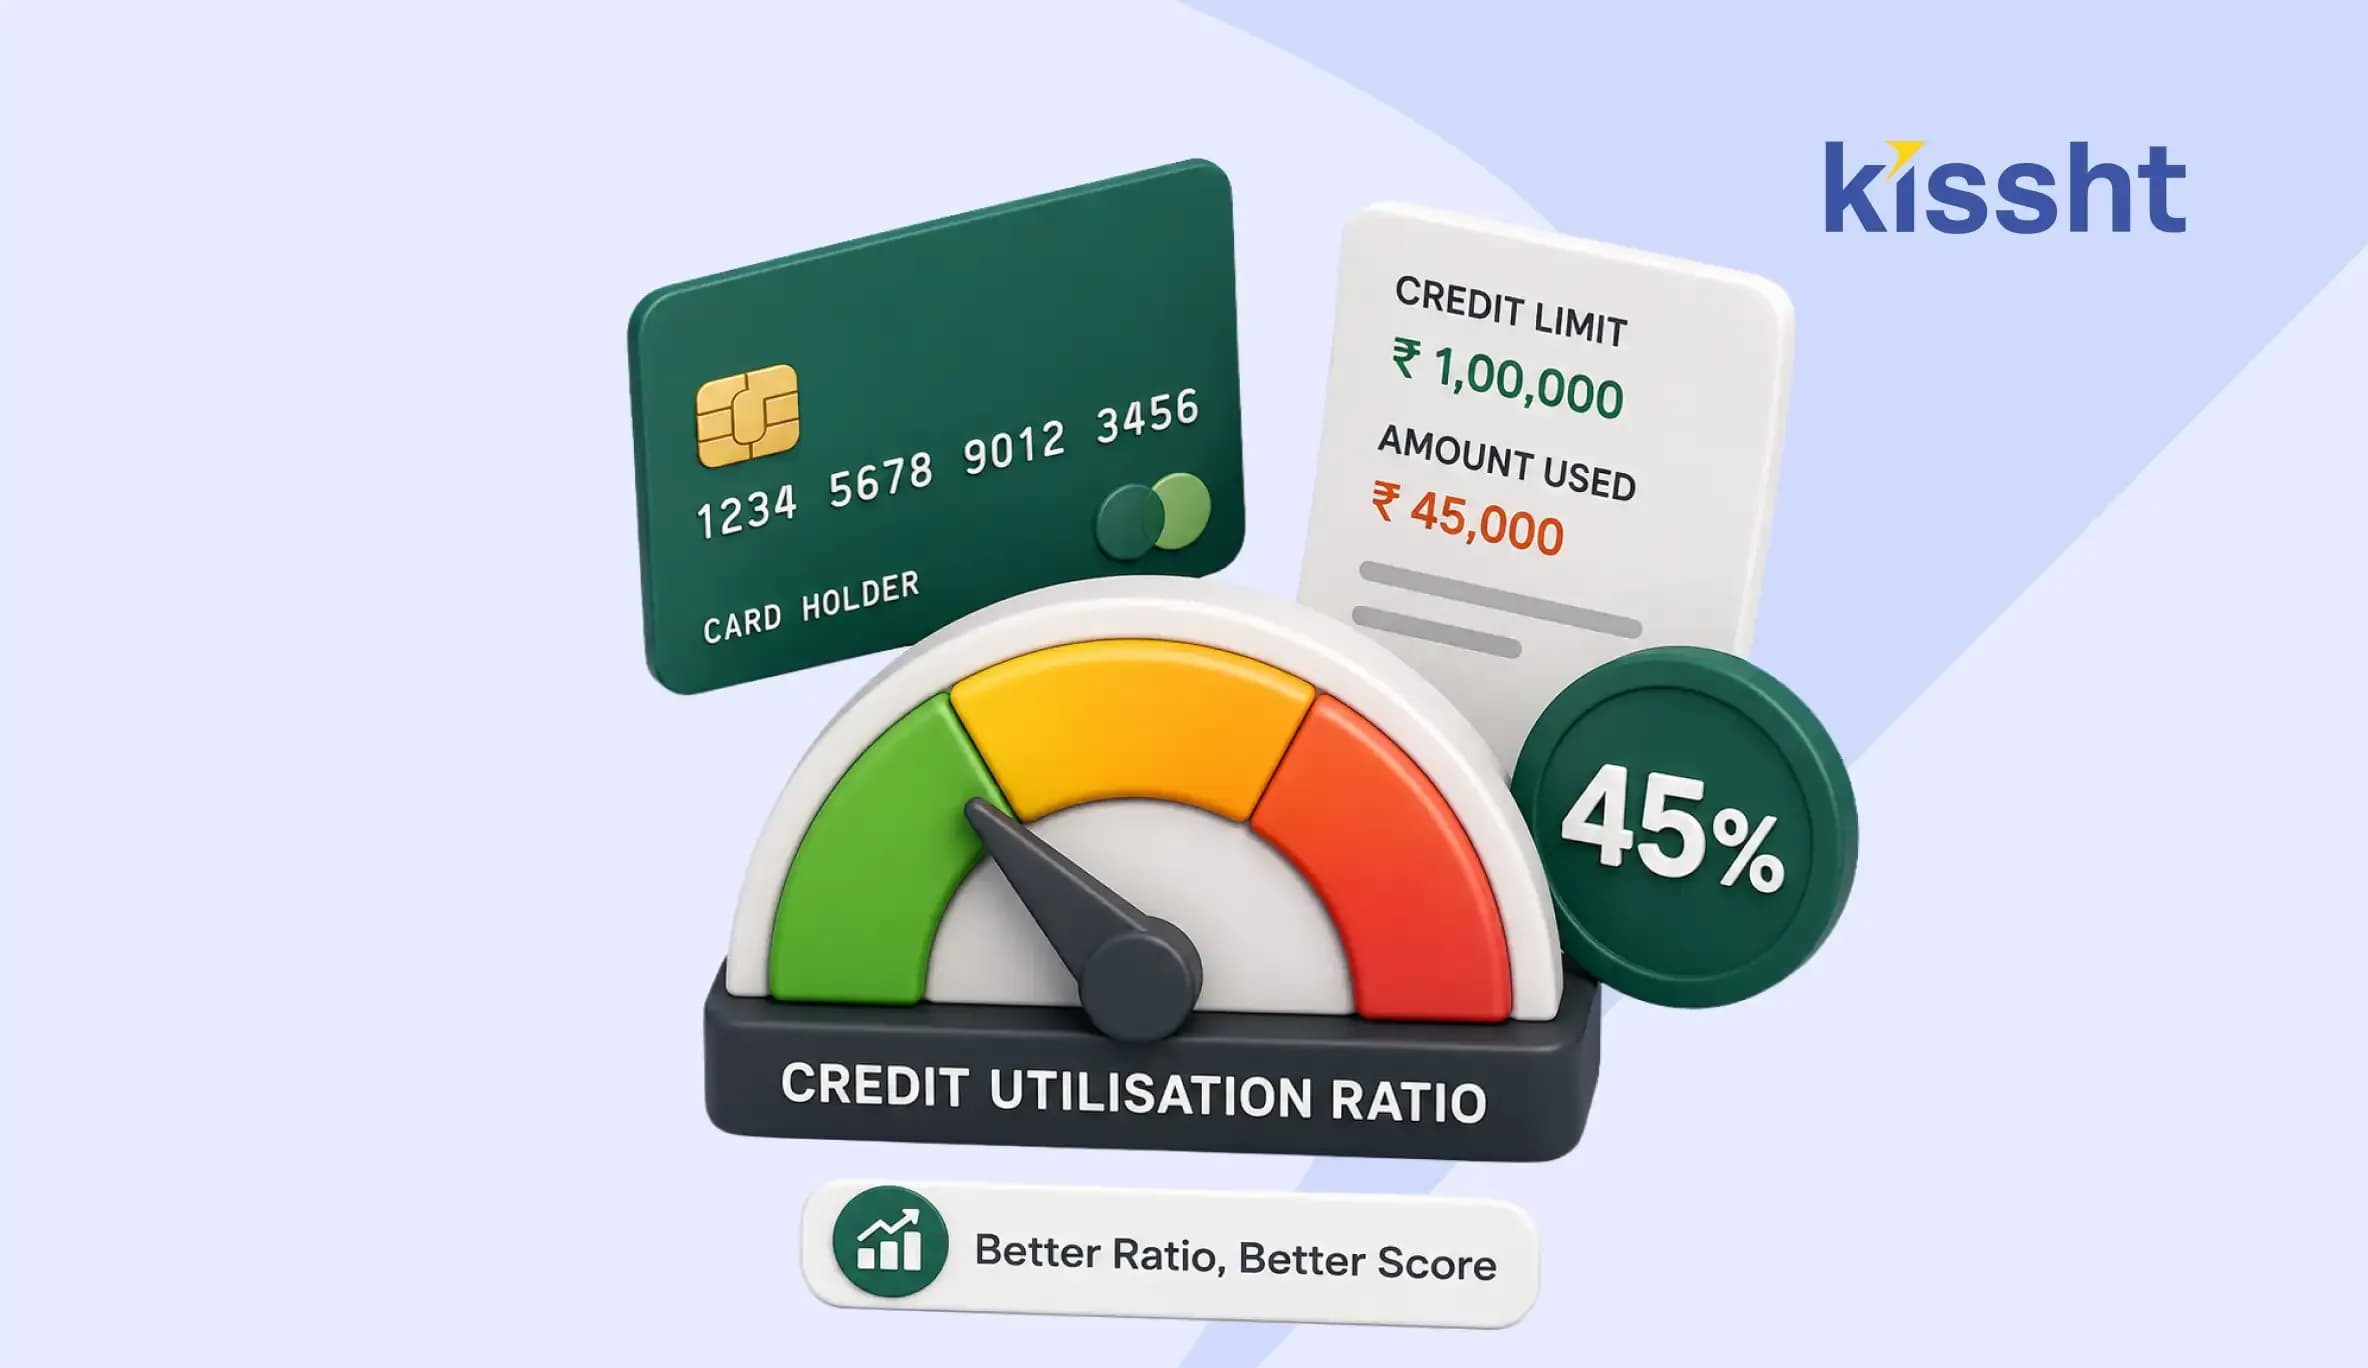
Credit Utilisation Ratio is the percentage of your total available credit limit that you currently use across your revolving credit accounts, such as credit cards.
What is a Credit Utilisation Ratio?
A Credit Utilisation Ratio measures how much of your available revolving credit you use at a given time. Lenders and credit bureaus use this ratio as an important indicator of your credit management habits.
The ratio compares your outstanding credit card balances with your total approved credit limit. For example, if your credit limit is Rs. 1,00,000 and your outstanding balance is Rs. 25,000, your credit utilisation ratio is 25%.
A lower credit utilisation ratio usually indicates responsible credit usage because it shows that you do not rely heavily on your available credit. A consistently high ratio may suggest higher credit dependency, which can affect your credit score. Thus, it is generally recommended to maintain a credit utilisation ratio below 30%.
Credit Utilisation Ratio = (Total Outstanding Debt ÷ Total Credit Limit) × 100
Credit Utilisation Ratio Range
| Range | Credit Usage |
|---|---|
| Below 10% | Excellent |
| 10% - 30% | Good / Ideal |
| 31% - 50% | Moderate |
| 51% - 75% | High |
| Above 75% | Very High |
Factors That Affect Credit Utilisation Ratio
- Total credit limit
- Outstanding credit card balance
- Multiple active credit cards
- Credit limit increase
- Large purchases
- Billing cycle timing
Tips to Reduce Credit Utilisation Ratio
- Pay credit card bills before the due date
- Make multiple payments each month
- Request a higher credit limit
- Spread expenses across multiple cards
- Keep old credit cards active
- Avoid unnecessary purchases
Credit Utilisation Ratio: Myths vs Facts
| Myths | Facts |
|---|---|
| A 0% credit utilisation ratio always leads to the highest credit score. | Responsible and regular credit card usage below 30% demonstrates that you actively and safely manage your available credit. |
| Credit utilisation ratio applies to all types of loans. | The credit utilisation ratio only applies to revolving credit accounts, such as credit cards and lines of credit. It does not apply to fixed installment loans. |
| A higher credit limit always increases your debt. | A higher credit limit only increases your available borrowing capacity. Your actual debt depends entirely on your spending and repayment habits. |
FAQs
Credit Utilisation Ratio is the percentage of your total available credit limit that you currently use across your revolving credit accounts, such as credit cards.
What is a good credit utilisation ratio?
A credit utilisation ratio below 30% is generally considered good. Many financial experts recommend keeping it below 10% for the best credit profile.
Is 40% credit utilisation bad?
A 40% credit utilisation ratio is higher than the commonly recommended level. It may affect your credit score if it remains high over time.
Can I have a 0% credit utilisation ratio?
Yes. A 0% credit utilisation ratio means you do not use your available revolving credit. However, a 0% ratio is not ideal because it does not help improve your credit score and can make you look inactive to lenders.
Does credit utilisation ratio affect loan approval?
Yes. Lenders often review your credit utilisation ratio along with your credit score and repayment history during loan evaluation.
Related Terms
Instant Loans at Your Fingertips
Apply nowPersonal Loan
Fast, hassle-free loan for your personal needs.
Business Loan
Fuel your business growth with quick approvals.

Loan Against Property
Unlock your property’s value with ease.

Credit Pulse
Boost your credit score with smart insights.
Track your credit score
Simply enter your mobile number to get a quick overview of your credit score.
Check Now