Borrower
Definition:
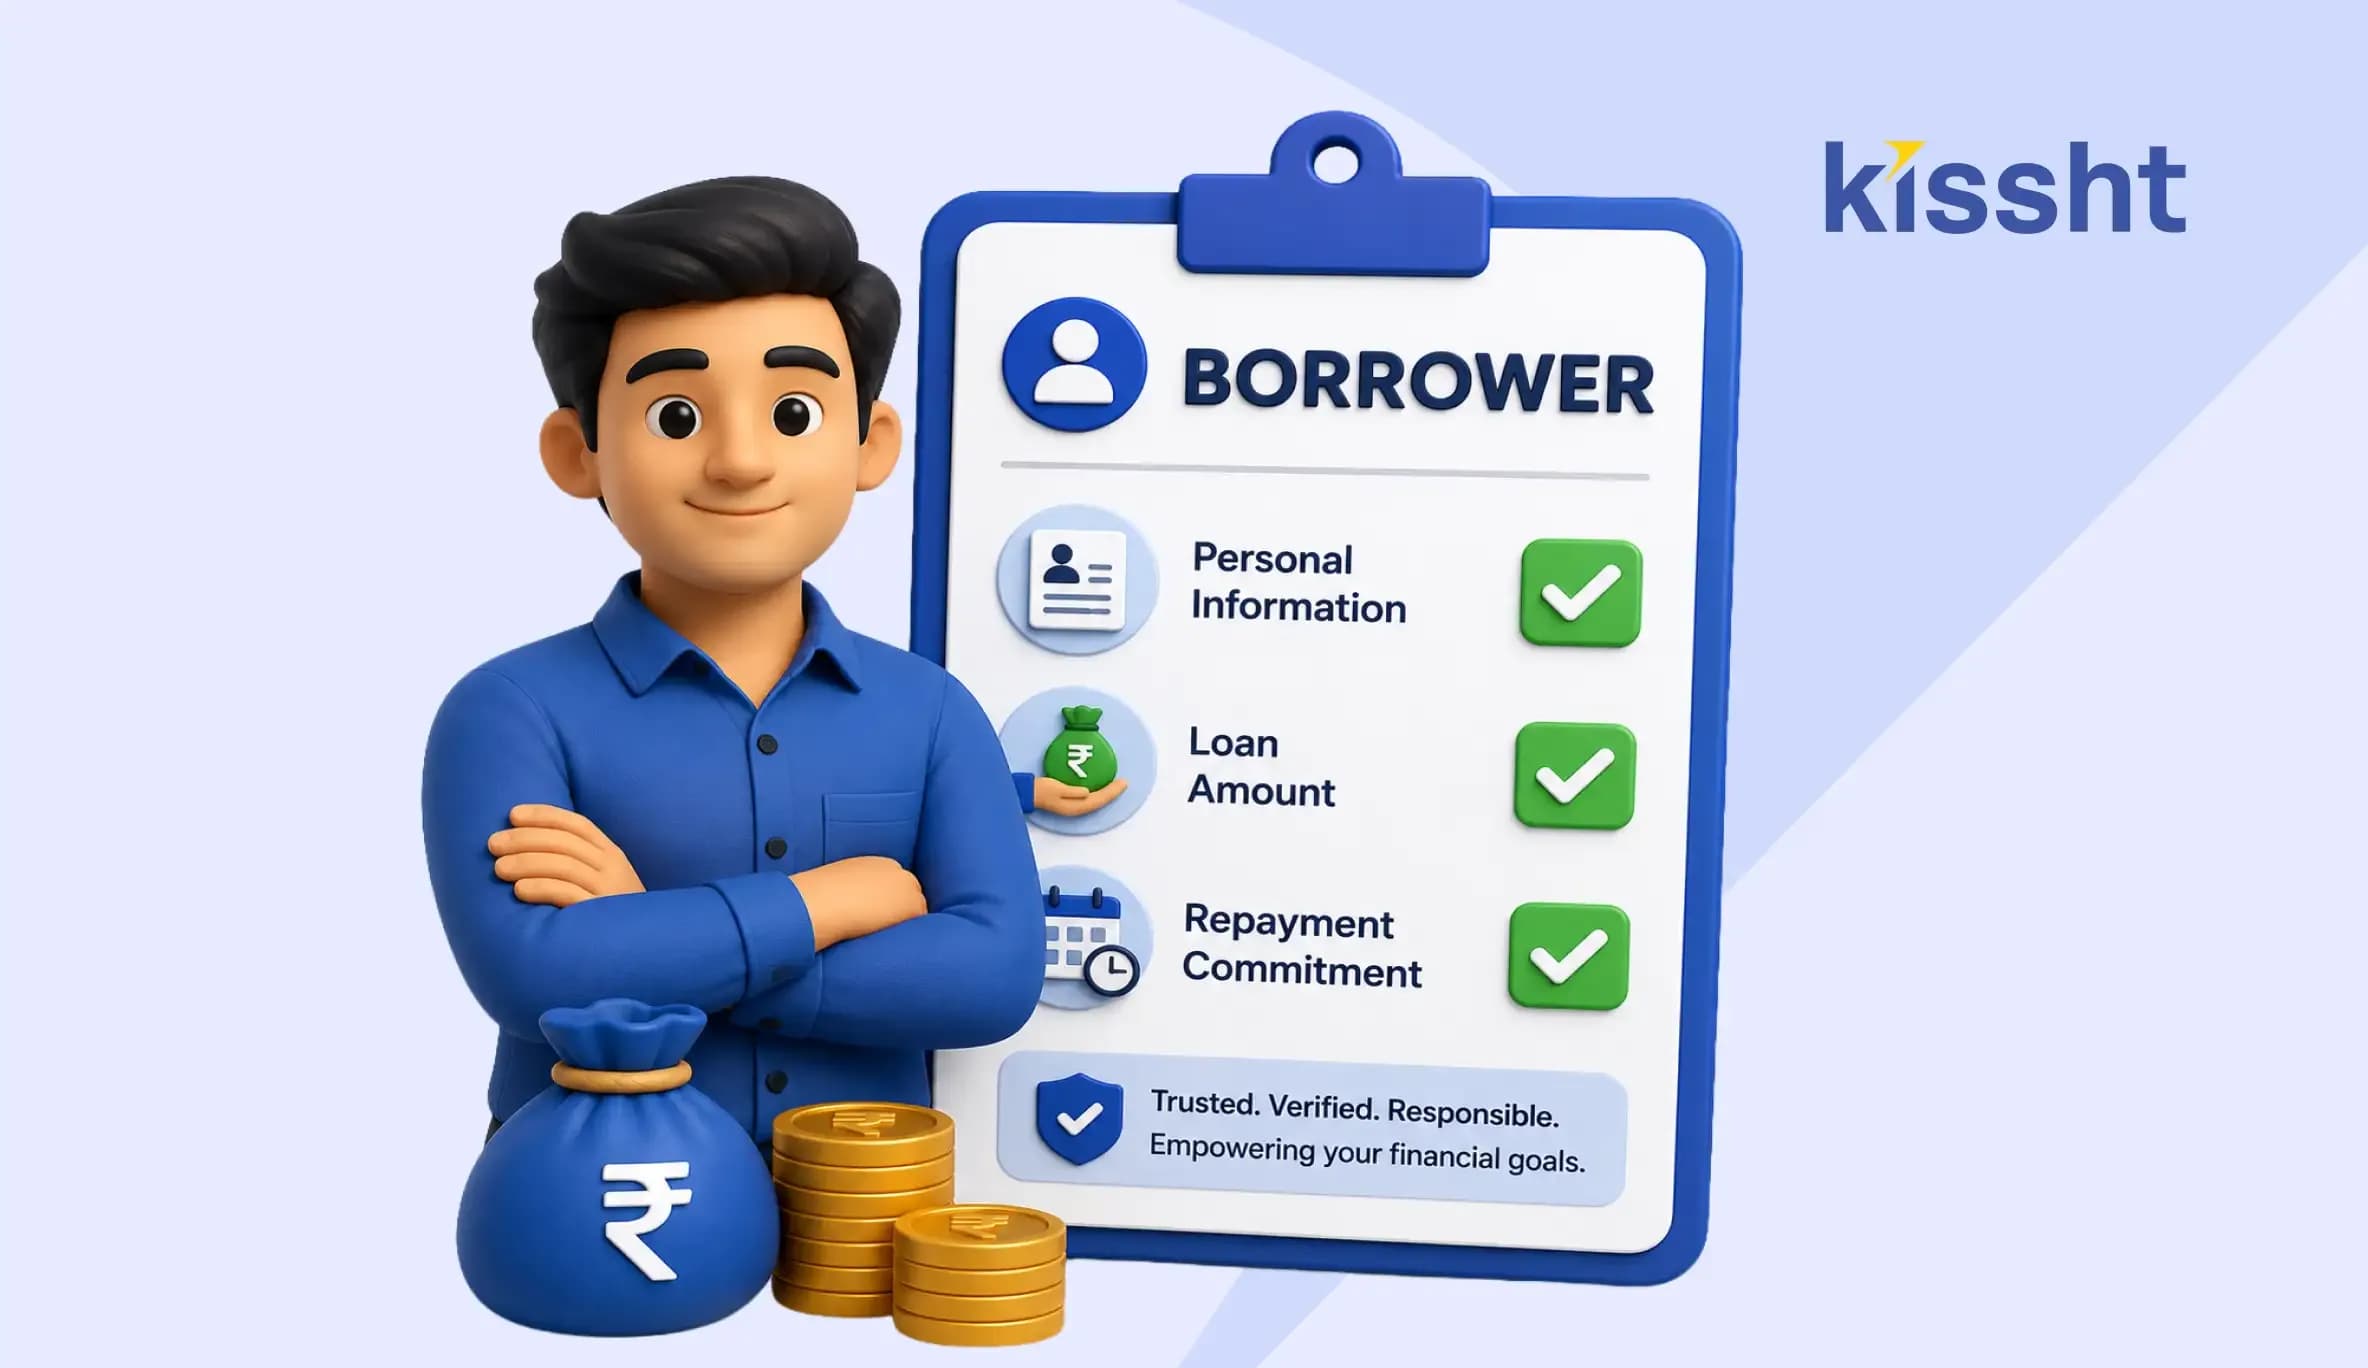
A borrower is an individual or business that receives money from a lender and agrees to repay it according to specified terms. Repayment usually includes both the principal amount and interest.
What Is a Borrower?
In simple terms, a borrower is the party responsible for returning the loan amount, along with applicable interest and charges, within the agreed repayment period.
For example, if you take a personal loan of ₹1 lakh from a lender, you become the borrower. The bank or financial institution providing the money is called the lender.
Borrowers may take different types of credit, including:
- Personal loans
- Home loans
- Education loans
- Business loans
- Vehicle loans
- Loans against property
- Credit card borrowing
The responsibilities of a borrower may differ depending on the loan type, amount and repayment terms. However, every borrower must understand the agreement and repay the amount on time.
How Does a Borrower Work?
The borrowing process usually involves the following steps:
-
Identifying the financial need
The borrower first decides why the money is required. It could be for an emergency, planned purchase, education expense or another genuine financial need.
-
Choosing a suitable loan
The borrower compares lenders based on the loan amount, interest rate, tenure, processing fee, eligibility criteria and repayment terms.
-
Submitting a loan application
The borrower provides details such as name, age, address, employment information, monthly income and existing financial obligations. Documents such as PAN, Aadhaar, income proof and bank statements may also be required.
-
Lender evaluation
The lender checks the borrower’s income, credit history, repayment capacity and existing debt. This helps the lender decide whether the applicant is eligible for the loan.
-
Reviewing the loan terms
If approved, the borrower receives details such as the sanctioned amount, interest rate, monthly EMI, tenure, processing fee and total repayment amount.
-
Accepting the loan
The borrower must carefully review the loan agreement and Key Fact Statement before accepting the offer.
-
Receiving the funds
Once the agreement and verification are completed, the loan amount is transferred to the borrower’s bank account or paid directly to the relevant seller or institution.
-
Repaying the loan
The borrower repays the loan through EMIs or another agreed repayment method. Payments must be made on or before the due date.
This process is common across traditional bank loans and instant personal loans offered through digital platforms.
Why Is a Borrower Important?
The borrower is central to any lending agreement because the loan is approved based on their ability and willingness to repay.
Being a responsible borrower is important for several reasons:
- Timely payments can support a healthy credit profile.
- Regular repayment helps avoid late payment charges.
- A good repayment history may improve future loan eligibility.
- Understanding loan terms reduces the risk of unexpected costs.
- Responsible borrowing helps prevent excessive debt.
A borrower’s repayment behaviour may be reported to credit bureaus. Delayed or missed EMIs can negatively affect the credit score, making it more difficult to obtain loans or credit cards in the future.
Example of a Borrower
Suppose Amit needs ₹80,000 to pay for urgent medical treatment. He compares different personal loan options and selects a loan with a tenure of 12 months.
The lender reviews Amit’s income, bank statements and credit history. After approval, the lender transfers ₹80,000 to his bank account.
Amit agrees to repay the loan through monthly EMIs. The EMI includes part of the principal amount and interest charged by the lender.
In this situation:
- Amit is the borrower.
- The financial institution is the lender.
- ₹80,000 is the principal amount.
- The monthly payment is the EMI.
- Twelve months is the loan tenure.
Amit must maintain sufficient balance in his bank account and ensure that every EMI is paid on time.
Responsibilities of a Borrower
A borrower has several responsibilities before and after taking a loan.
Provide accurate information
All personal, employment and income information submitted to the lender should be correct. Providing false information may lead to rejection or legal consequences.
Read the loan documents
The borrower should review the interest rate, annual percentage rate, processing fee, late payment charges, repayment schedule and foreclosure conditions.
Pay EMIs on time
Delayed payments may result in penalties and may affect the borrower’s credit report.
Inform the lender about difficulties
If the borrower is unable to make a payment due to a genuine financial problem, they should contact the lender rather than ignore calls or notices.
Keep repayment records
Borrowers should retain payment receipts, bank statements, loan closure letters and no-dues certificates for future reference.
Things to Consider Before Becoming a Borrower
Before accepting a loan, consider the following:
- Borrow only the amount you genuinely need.
- Check the total cost of borrowing.
- Compare interest rates and charges.
- Choose an EMI that fits your monthly budget.
- Avoid applying for several loans at the same time.
- Read the cancellation and foreclosure terms.
- Confirm how delayed payments affect your credit score.
- Keep the lender’s customer support details available.
A common mistake is focusing only on quick approval and ignoring the repayment obligation. Borrowers should evaluate affordability before accepting any loan.
Conclusion
A borrower is an individual or organisation that receives funds from a lender and agrees to repay them within a specified period. Becoming a borrower involves more than receiving money. It also includes understanding the loan agreement, managing EMIs and meeting repayment obligations.
A well-informed borrower compares loan options, checks the total cost, reads all documents and borrows according to repayment capacity. Responsible borrowing can help meet important financial needs without creating unnecessary financial stress.
FAQs
Can a borrower take more than one loan?
Yes, a borrower can have multiple loans. However, lenders consider existing EMIs and total debt before approving another loan.
Is a borrower always an individual?
No. A borrower may be an individual, company, partnership firm, trust or another legal entity.
What happens if a borrower misses an EMI?
The lender may charge late fees or penal charges. The missed payment may also be reported to credit bureaus and affect the borrower’s credit score.
What is the difference between a borrower and a co-borrower?
The main borrower applies for and receives the loan. A co-borrower jointly applies and shares equal responsibility for repayment.
Related Terms
Instant Loans at Your Fingertips
Apply nowPersonal Loan
Fast, hassle-free loan for your personal needs.
Business Loan
Fuel your business growth with quick approvals.

Loan Against Property
Unlock your property’s value with ease.

Credit Pulse
Boost your credit score with smart insights.
Track your credit score
Simply enter your mobile number to get a quick overview of your credit score.
Check Now